

 62 / 76

62
PERFORMANCES
FINANCIAL
OVERVIEW
The year 2013 reflects the Group’s growth dynamic, illustrated by a confirmed increase
of sales – both in France and internationally – and by the improved recurring operating
income (+9.8%at constant exchange rates) in a difficult economic context.
In France, Carrefour saw a return to growth, with a rise in organic sales excluding petrol
(+1%). Performance in other European countries recovered significantly in the second half
of the year, notably in Spain. In emerging countries, recurring operating income improved by
8.5%at constant exchange rates.
Carrefour continued to strengthen its financial structure in 2013: debt was reduced by over
€203 million to reach €4.1 billion and the net debt to EBITDA ratio improved by 10%,
to 1.1x. At the same time, the Group resumed its investments, which grew by 44%
to €2.2 billion.
In accordance with IFRS 5, income and expenses relating to discontinued operations were reclassified on the “Net income of discontinued
operations” lineoftheconsolidated incomestatement in2012and2013.The2012accountshavebeenadjusted inaccordancewiththeapplication
onJanuary1,2013of IAS19(EmployeeBenefits).
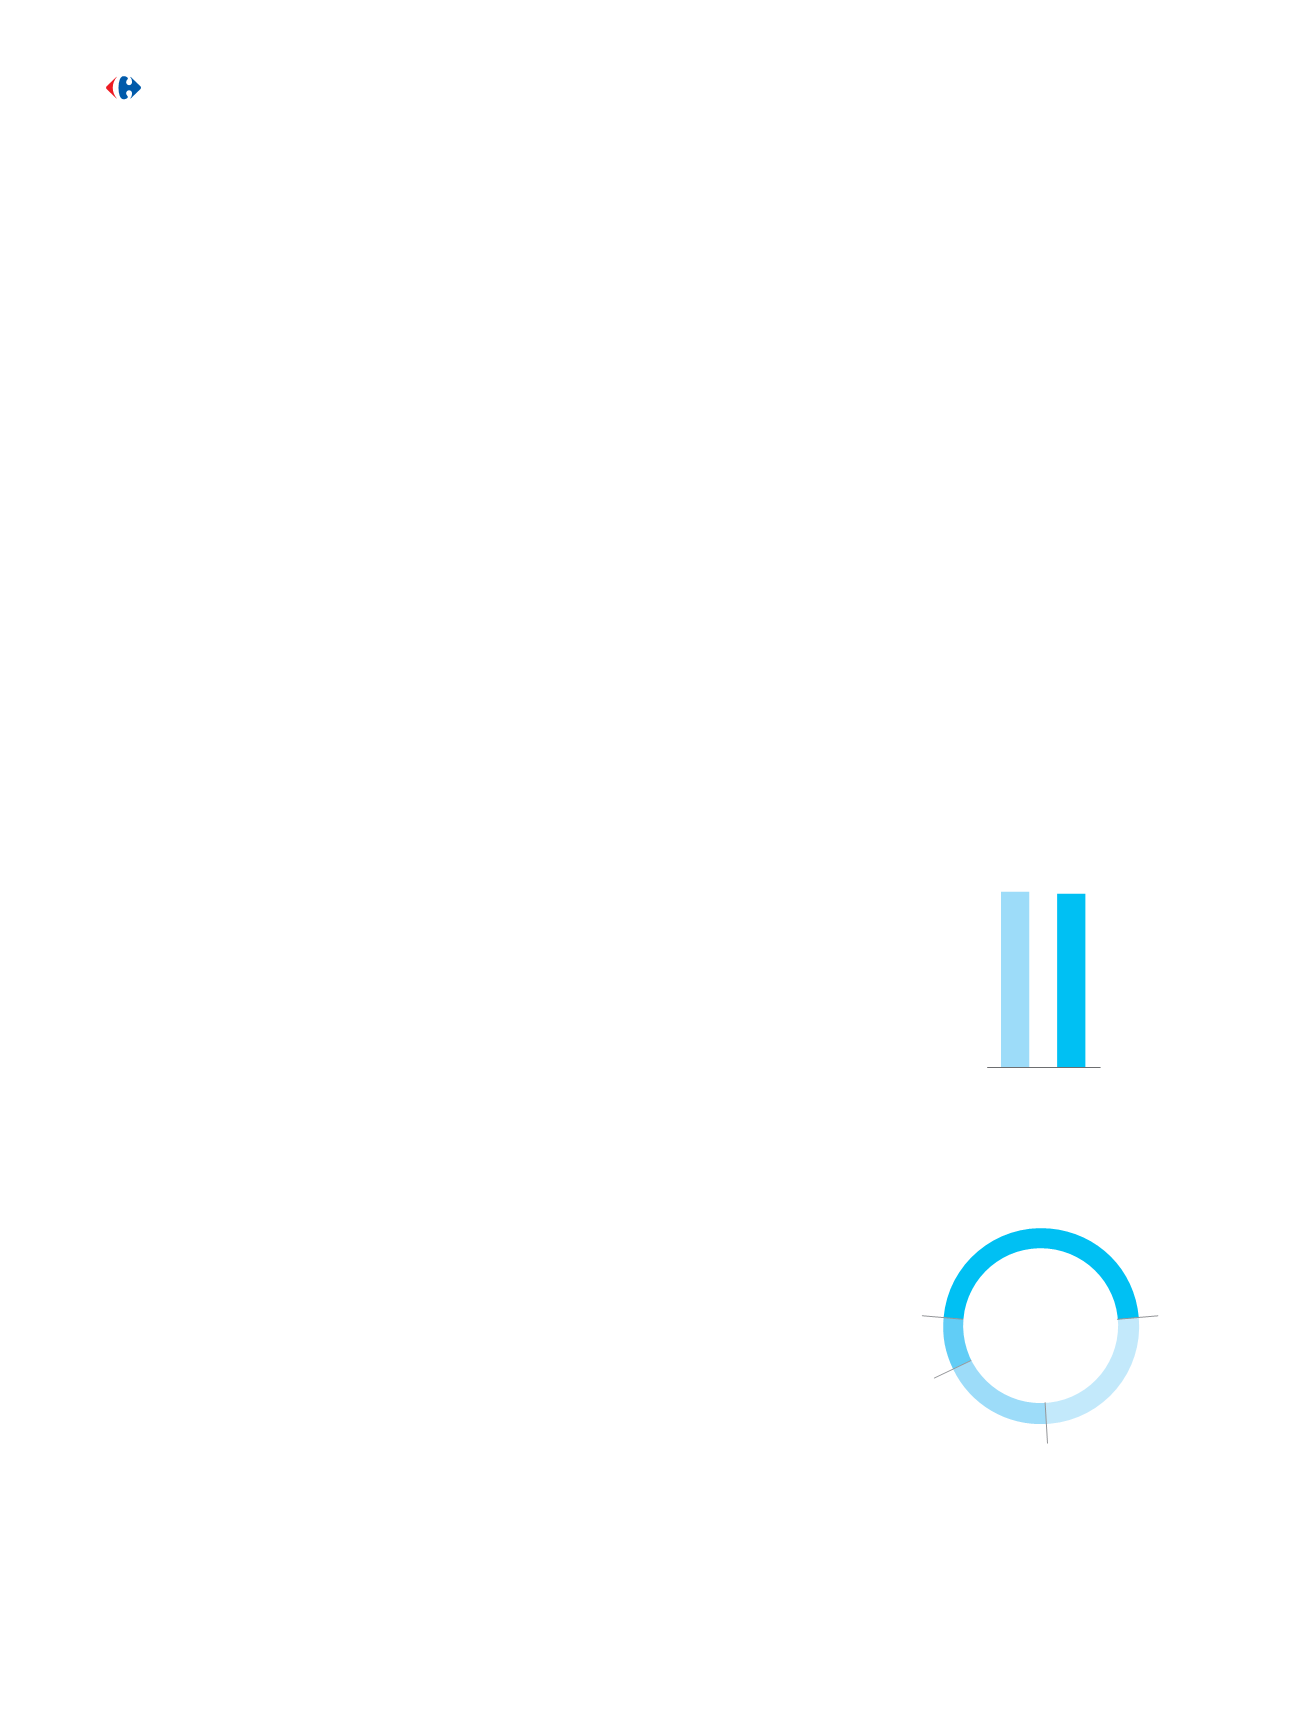
Net sales rose by 2% at constant exchange
rates compared with 2012 (–1.0% at current
exchange rates) and an increase in sales was
seen both in France and internationally.
In France, net sales grew organically by +1.0%
excluding petrol (+0.3% on a reported basis):
attractiveness improved across our various activ-
ities, with regular headway made in terms of
price image, a higher number of check-out trans-
actions, and an increase in overall customer
satisfaction.
In other countries in Europe, net sales fell by
2.9%: growth in sales showed a clear improve-
Net sales
€74
,
888
million
+2.0%COMPAREDWITH2012
(at constant exchange rates)
ment in the second half of the year, particularly
in Spain, where like-for-like store sales grew in
the fourth quarter for the first time since 2008.
In Latin America, organic sales were up sharply
by +12.3%, over what was already a high basis
of comparison in 2012; remarkable progress
was made in terms of organic sales in Brazil
and Argentina, where Carrefour is consolidat-
ing its position as a food retail leader.
In Asia, the rate of organic growth of sales quick-
ened in 2013 (+2.2%) and China continues to
build a long-term position, opening 20 new
hypermarkets.
0
75500
75,673
2012
2013
74,888
Net sales
(in €M)
Net sales by geographic region
(in €M)
France
35,438
Asia
6,443
Latin
America
13,786
Other countries
in Europe
19,220